Bank of Uganda Rate Hike and Uganda's Crypto Market
INTRODUCTION A decision made in the central bank’s meeting room may seem far removed from someone buying USDT on their phone in Kampala. But the two are connected by something both traditional finance and cryptocurrency depend on: the cost and availability of money.
The Bank of Uganda’s reported decision to raise its Central Bank Rate from 9.75% to 12% on October 14 puts that relationship into focus. The move comes amid pressure on the shilling and concerns about inflation, bringing fresh questions about how households, traders and businesses will manage their money in the months ahead.
For Uganda’s cryptocurrency market, the consequences are unlikely to be straightforward. A higher interest rate does not automatically send Bitcoin prices down or push USDT demand up. Its significance lies in the financial decisions people may make in response.
When the cost of money changes, crypto feels it too
An increase in the Central Bank Rate can make borrowing more expensive as commercial banks adjust their lending conditions. For businesses already managing tight margins, that can mean less money available for expansion, technology investments or other operating expenses.
Crypto-related businesses are not exempt. Companies involved in digital payments, cryptocurrency exchanges and related technology services may need to reconsider their spending if financing becomes more expensive.
The effect on individual traders could be different. Someone who borrows to fund investments may become more cautious, while someone who uses cryptocurrency to receive payments from abroad may continue doing so regardless of the interest rate.
That distinction matters in Uganda, where cryptocurrency activity can serve several purposes. For some people, it is speculative trading. For others, digital assets are part of how they handle international transactions or move money between supported platforms.
Treating all these users as a single group would miss the real story.
The shilling may matter more than the rate itself
One of the most important questions is what happens to the Ugandan shilling.
When a cryptocurrency is priced internationally in US dollars, its cost in Uganda can change even if its dollar price remains stable. A movement in the exchange rate can affect how many shillings a buyer needs to purchase the same amount of Bitcoin or USDT.
Consider a simple example. If an asset costs $100, its equivalent at UGX 3,800 per dollar is UGX 380,000. At UGX 4,000 per dollar, the equivalent becomes UGX 400,000, before transaction fees and exchange spreads.
Nothing about the asset’s dollar price has changed. The difference comes from the exchange rate.
A higher policy rate can influence currency-market expectations, but it does not guarantee that the shilling will strengthen. International oil prices, demand for foreign currency, trade flows and wider financial conditions can all influence the outcome.
For local crypto buyers, this means watching the shilling alongside international cryptocurrency prices. Looking at Bitcoin’s dollar price alone may not explain why its local price has changed.
Could USDT become more attractive?
USDT occupies a different position from Bitcoin in this discussion. It is designed to track the US dollar, so people generally use it for dollar-linked exposure and transfers rather than for the same price speculation associated with Bitcoin.
If concerns about the shilling persist, some Ugandans may become more interested in dollar-linked digital assets. That is one possible outcome, particularly among people who already use USDT for international transactions.
But a rise in interest should not be assumed.
If the shilling stabilises, or if conventional financial products become more attractive, some users may have less incentive to seek dollar-linked alternatives. The cost of acquiring USDT also matters. Network fees, conversion charges, local supply and the difference between buying and selling prices can make a meaningful difference.
There is another distinction worth making: USDT is not identical to holding US dollars in a bank account. It carries risks relating to its issuer, custody arrangements, market liquidity and the platforms through which it is purchased or redeemed.
The more useful question is whether users find USDT practical and cost-effective for their particular needs—not whether the rate hike alone will make it more popular.
Higher rates could change where people put their money
Interest rates also affect the choices people make about savings and investments.
If commercial banks offer more attractive deposit rates, some savers may reconsider how much money they want to expose to volatile assets. Others may continue using cryptocurrency because their main purpose is transferring funds, accessing particular markets or maintaining a digital asset position.
These are different financial decisions, and they should not be confused.
Bitcoin does not become less volatile simply because conventional interest rates rise. Nor does a higher policy rate make every bank deposit more attractive after inflation, fees and other considerations are taken into account.
What could change is the calculation people make before committing money to crypto trading. Someone facing higher loan repayments or rising household expenses may decide to reduce speculative trading. Another person with an established business need for digital payments may see little reason to change their routine.
The effect on Uganda’s market will depend on which of these behaviours becomes more common. Without reliable local trading data, it is too early to claim that the rate hike has already increased or reduced cryptocurrency activity.
The pressure on crypto businesses may be less visible
For businesses operating around cryptocurrency, the immediate concern may not be Bitcoin’s next price movement. It may be the cost of running the business.
Technology maintenance, cybersecurity, customer support, compliance and payment processing all require funding. Companies that rely on credit could find their plans more expensive to finance if lending rates rise.
Smaller operators may feel the pressure sooner than established businesses with stronger cash reserves. Some could delay expansion or focus on improving existing services rather than taking on additional costs.
At the same time, a changing financial environment can create opportunities for businesses that help customers understand digital payments, compare transaction costs and navigate cross-border transfers.
Whether those opportunities translate into growth will depend on customer demand, operating costs and the rules applicable to each service. A tighter monetary environment alone is not enough to predict which companies will succeed.
What happens next?
The impact of the rate hike will become clearer through developments in the months ahead, rather than through the announcement alone.
The shilling’s performance will be important, as will changes in commercial lending and deposit rates. Local USDT prices, conversion spreads and customer activity could offer further clues about how people are responding.
Global cryptocurrency markets will remain another major influence. Bitcoin and other digital assets respond to international economic conditions and market sentiment, which can sometimes outweigh developments in a single country.
For now, the most defensible conclusion is that Uganda’s higher policy rate changes the financial environment in which crypto businesses and users operate. It does not determine the market’s direction by itself.
For anyone buying USDT, the practical issue is the combined effect of the exchange rate, fees and the intended use of the asset. For businesses, it is whether changing financing costs and customer behaviour affect their margins. For the wider industry, it is whether digital assets continue to meet genuine needs as the cost of conventional money changes.
Uganda’s crypto market will not respond to monetary policy in exactly the same way as its banking sector. But neither can it be separated from the economy around it.
This article is for informational purposes only and does not constitute financial or investment advice. Readers should verify official monetary policy announcements and assess the risks associated with cryptocurrency transactions independently.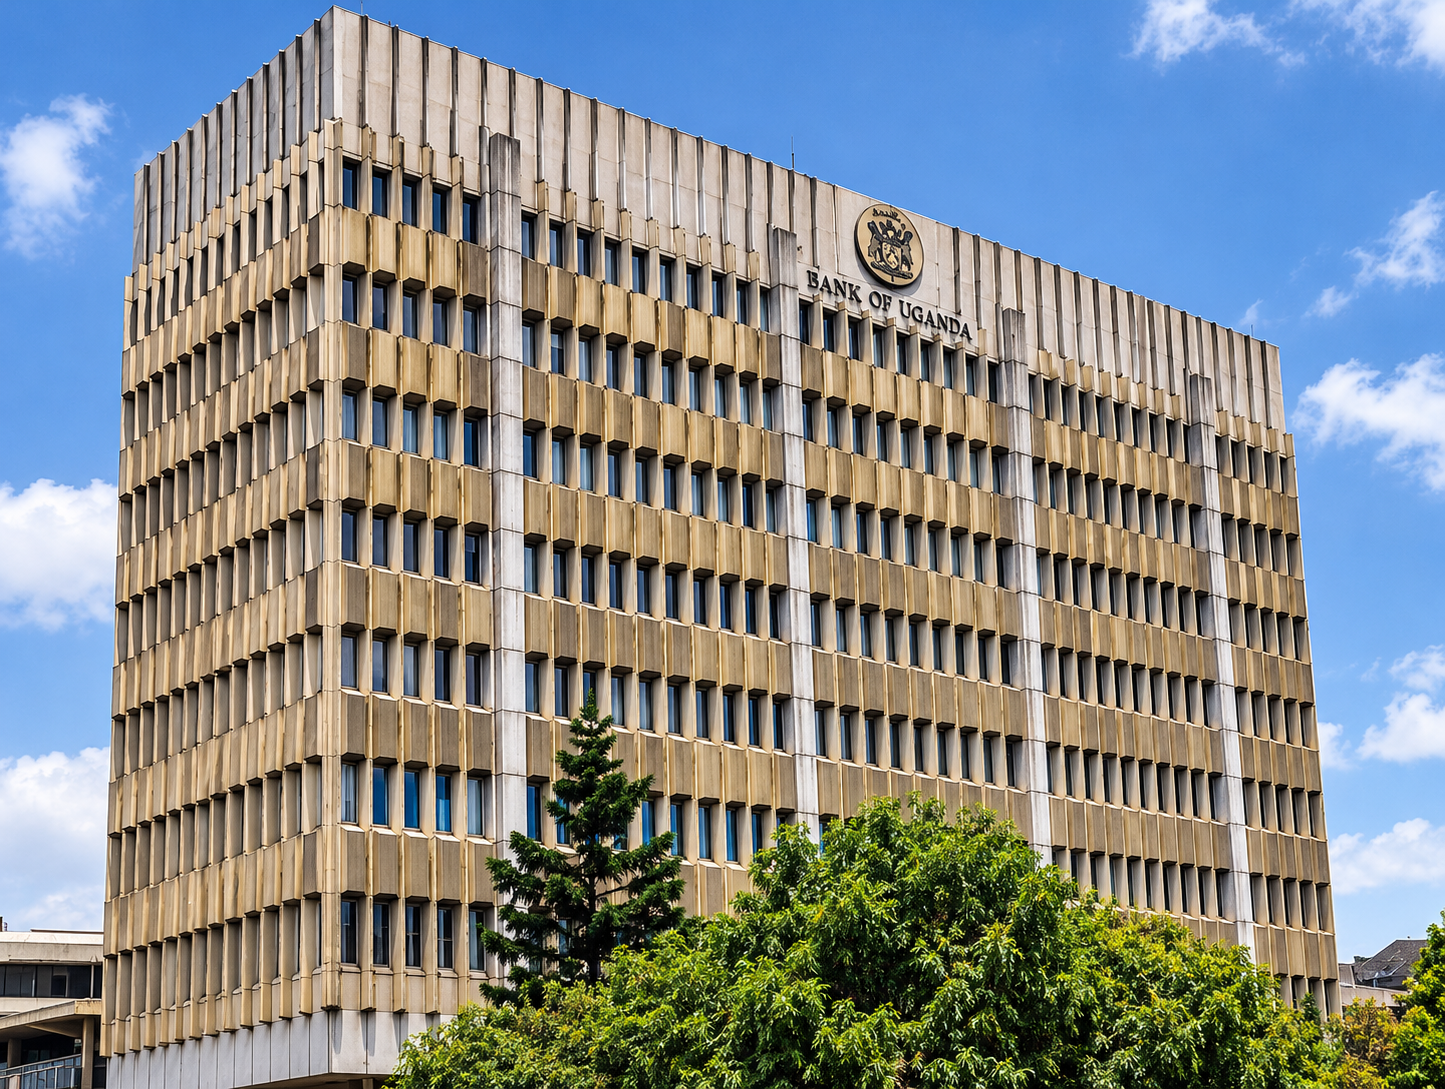
Still have questions?
Message us on WhatsApp — we reply instantly and can walk you through your exchange step by step.
Chat on WhatsApp